Mortgage Calculator: Estimate Your Monthly Payment, PMI and Payoff
Estimate your monthly mortgage payment with taxes, insurance, PMI and HOA — plus the full amortization schedule.
Formula
Monthly principal & interest = L × r(1+r)^n ÷ ((1+r)^n − 1), where L is the loan amount, r is the monthly rate (annual rate ÷ 12 ÷ 100), and n is the number of payments. At a 0% rate, the payment is simply the loan ÷ n. Property tax and insurance are added as one-twelfth of their annual amounts; PMI and HOA are added as monthly amounts.
Worked example
A $400,000 home with 20% down ($80,000) at 6.5% for 30 years: loan $320,000, monthly rate 0.0054167, 360 payments. P&I = $2,022.62 per month; total interest over 30 years = $408,142.36.
How to use the mortgage calculator
This mortgage calculator turns a home price, down payment, interest rate and loan term into a monthly payment. It then shows what that payment is made of and how fast the loan shrinks.
This is an estimate for planning — actual payments, PMI, taxes and insurance come from your lender, tax authority and insurer.
Fill in the four required fields
- Home price in dollars.
- Down payment type: % of home price (the default) or a $ amount, then enter the down payment.
- Interest rate per year, from 0 to 25%.
- Loan term: 30, 20, 15 or 10 years fixed. The default is 30.
With only these four fields filled in, the result is labeled "Monthly principal & interest."
Add the costs that sit on top
Open the Advanced options to enter property tax ($ per year), home insurance ($ per year), PMI ($ per month), HOA dues ($ per month) and an extra principal payment ($ per month). You can also add a loan start date, which sets the payoff month and year.
Once you enter any of these, the headline becomes your total monthly payment. If your down payment is under 20% and you leave PMI blank, the calculator estimates it at 0.5% of the loan per year and labels it "estimated."
What you get back
- A breakdown: loan amount, monthly principal and interest, tax, insurance, PMI, HOA, total interest, total PMI paid, interest saved by extra payments, PMI end month and payoff date.
- A yearly amortization table showing total paid, principal, interest and balance.
- An interactive chart of cumulative principal versus cumulative interest.
What it does not cover
The calculator models fixed-rate loans only, not adjustable-rate mortgages. It assumes tax and insurance stay flat, though they usually rise. The 0.5% PMI estimate is rough, because real PMI depends on your credit score, loan type and lender. Closing costs, points and origination fees are not included, and escrow is simplified.
Comparing a mortgage with a car or personal loan? The loan EMI calculator handles other monthly loan payments.
What makes up your monthly mortgage payment
Lenders often call the full payment PITI: principal, interest, taxes and insurance. Add PMI and HOA dues where they apply. For a plain-English definition, see the CFPB's explanation of PITI.
The formula behind principal and interest
Monthly P&I = L × r(1+r)n ÷ ((1+r)n − 1)
L is the loan amount, r is the monthly rate (annual rate ÷ 12 ÷ 100) and n is the number of payments. At a 0% rate, the payment is simply the loan ÷ n.
Worked example: $400,000 home, 20% down, 6.5%, 30 years
- Down payment: $400,000 × 20% = $80,000. Loan: L = $320,000.
- Monthly rate: r = 6.5 ÷ 12 ÷ 100 = 0.00541667.
- Payments: n = 30 × 12 = 360.
- (1+r)360 ≈ 6.992.
- P&I = 320,000 × 0.00541667 × 6.992 ÷ 5.992 = $2,022.62 per month.
- Total interest = $2,022.62 × 360 − $320,000 = $408,142.36.
The calculator uses the unrounded payment, so total interest comes to $408,142.36 rather than $408,143.20 (the rounded payment × 360).
Adding taxes, insurance and PMI
Property tax and insurance are divided by 12. PMI and HOA are entered as monthly amounts. Here is a second example: $400,000 home, 10% down, 7%, 30 years, $4,400 a year in tax and $1,800 a year in insurance.
| Component | Monthly | How it's calculated |
|---|---|---|
| Principal & interest | $2,395.09 | $360,000 loan, 7%, 360 payments |
| Property tax | $366.67 | $4,400 ÷ 12 |
| Home insurance | $150.00 | $1,800 ÷ 12 |
| PMI (estimated) | $150.00 | $360,000 × 0.5% ÷ 12 |
| Total | $3,061.76 |
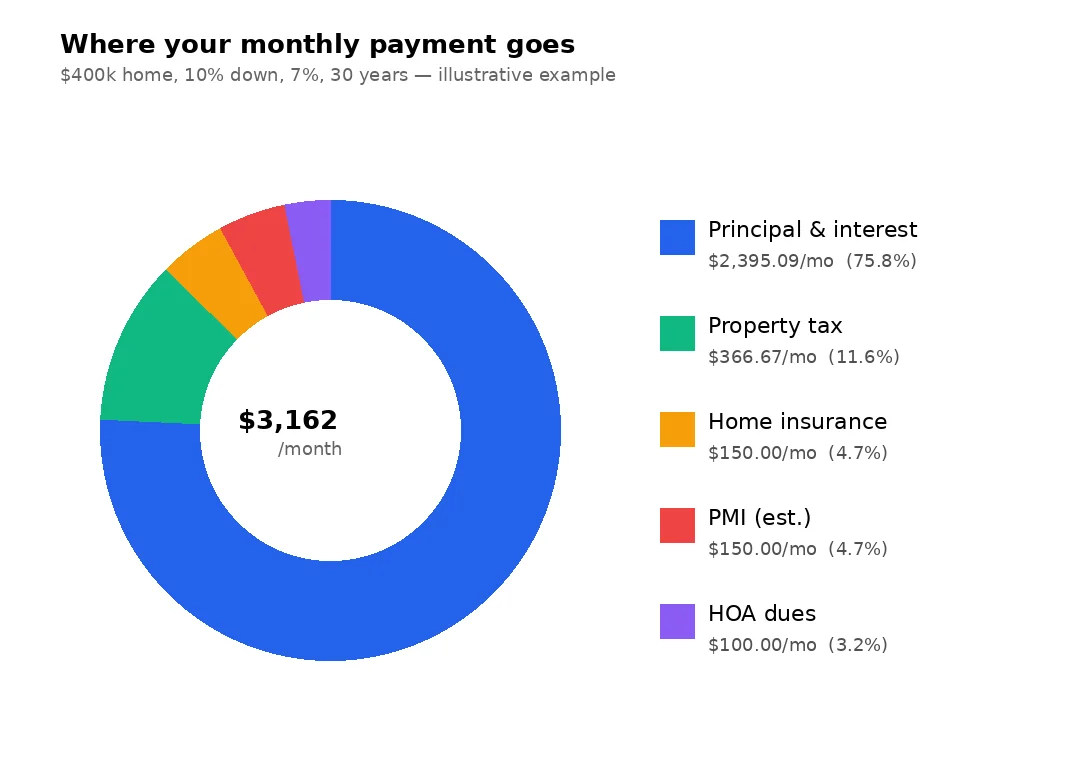
The chart adds $100 a month in HOA dues to the same example, which brings the total to about $3,162.
To see why the two numbers differ, read the CFPB on principal-and-interest vs. total monthly payment. To find what share of your payment one cost takes up, a percentage calculator works it out quickly.
How to pay off your mortgage years early
Early payments go mostly to interest. On the $320,000 loan above, the first payment is $1,733.33 of interest ($320,000 × 0.00541667) and only $289.29 of principal. That is about 86% interest.
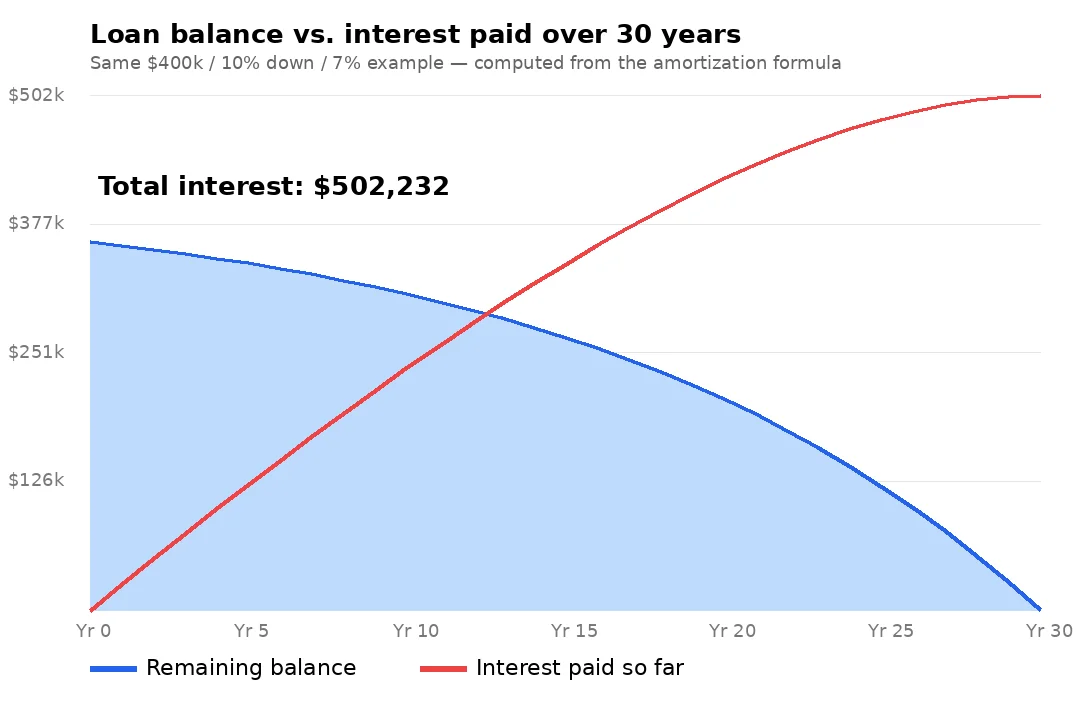
Interest is charged each month on what you still owe, much like how compound interest builds in reverse. Every extra dollar you pay lowers the balance that interest is charged on.
Example: an extra $200 a month
Extra payments go 100% to principal. Take the first example and add $200 a month in the Advanced options:
- The loan is paid off in 281 months (23 years 5 months) instead of 360.
- That is 79 months, or 6 years 7 months, early.
- Total interest drops from $408,142.36 to $302,713.69.
- You save $105,428.67 in interest.
Comparing a 15-year and a 30-year term
The table keeps the same $320,000 loan and 6.5% rate so the comparison is clean. The 15-year row is calculated with the same formula.
| Scenario | Monthly P&I | Payoff | Total interest |
|---|---|---|---|
| 30-year fixed | $2,022.62 | 360 months | $408,142.36 |
| 30-year + $200 extra | $2,222.62 paid | 281 months | $302,713.69 |
| 15-year fixed | about $2,788 | 180 months | about $181,800 |
The 15-year payment is about $765 higher each month, but it cuts interest by roughly $226,000. Lenders often price 15- and 30-year loans differently, so enter your actual quote.
An extra payment is a flexible middle path. You can add it in some months and skip it in others.
PMI: what it costs and when it disappears
Private mortgage insurance (PMI) usually applies to conventional loans when you put down less than 20%. It protects the lender, not you, and it adds to your monthly payment.
What PMI costs
The typical US range is about 0.3% to 1.9% of the loan per year. On a $360,000 loan, that is roughly $90 to $570 a month. Your rate depends on your credit score, loan type and lender.
If you enter nothing, the calculator estimates 0.5% a year, which is $360,000 × 0.5% ÷ 12 = $150 a month. It labels the line "estimated." Replace it with your lender's figure as soon as you have one.
When PMI ends
The calculator charges PMI every month your balance is above 80% of the home value. On the $400,000 home, 80% is $320,000. With 10% down at 7%, the balance first falls to or below $320,000 after month 101, which is 8 years 5 months. The "PMI end month" row shows this date for your own numbers.
Federal law generally lets you ask your lender to cancel PMI at 80%. It generally ends automatically at 78% of the original value, which is $312,000 here. Your lender's rules decide the actual date, so ask them.
How to shorten the PMI period
- Put down more at the start. A 20% down payment avoids PMI entirely.
- Make extra principal payments. They should bring the 80% mark closer.
- Compare the "total PMI paid" row across down payment amounts to see what each choice costs.
Frequently asked questions
How much is the monthly payment on a $400,000 mortgage?
It depends on the rate, term and down payment. With 20% down at 6.5% over 30 years, principal and interest is $2,022.62 a month on a $320,000 loan. Taxes, insurance, PMI and HOA dues come on top, so enter them in Advanced for a full figure.
How do I calculate a mortgage payment by hand?
Use Monthly P&I = L × r(1+r)^n ÷ ((1+r)^n − 1), where L is the loan, r the monthly rate and n the number of payments. For $320,000 at 6.5% for 30 years, that gives $2,022.62. Add taxes, insurance, PMI and HOA separately.
When does PMI go away?
PMI ends once your balance reaches 80% of the home's value, which you can request, and it generally drops off automatically at 78% of the original value. On a $400,000 home with 10% down at 7%, the calculator shows PMI ending after month 101, about 8 years 5 months.
How much does PMI cost?
Typical US PMI runs about 0.3% to 1.9% of the loan per year. On a $360,000 loan, that's roughly $90 to $570 a month. The calculator estimates 0.5% a year, or $150 a month, when you put down under 20% and don't enter PMI.
Does paying extra each month really save that much?
Yes. Extra payments go 100% to principal, so that part of the balance stops accruing interest. On a $320,000 loan at 6.5%, an extra $200 a month ends the loan in 281 months instead of 360 and saves $105,428.67 in interest. Ask your lender whether it charges prepayment penalties first.
Related calculators
Loan EMI Calculator
Estimate your monthly loan payment from amount, rate and term.
Use calculatorCompound Interest Calculator
See how your savings grow with compounding interest over time.
Use calculator
Percentage Calculator
Find what P% of any number is — instant answers with the formula shown.
Use calculator